The International Monetary Fund (IMF) has concluded the fourth review of Sierra Leone’s Extended Credit Facility (ECF) Programme and the first review of the Resilience and Sustainability Facility (RSF), commending the country’s efforts to restore macroeconomic stability while cautioning against emerging global risks that could threaten recent gains.
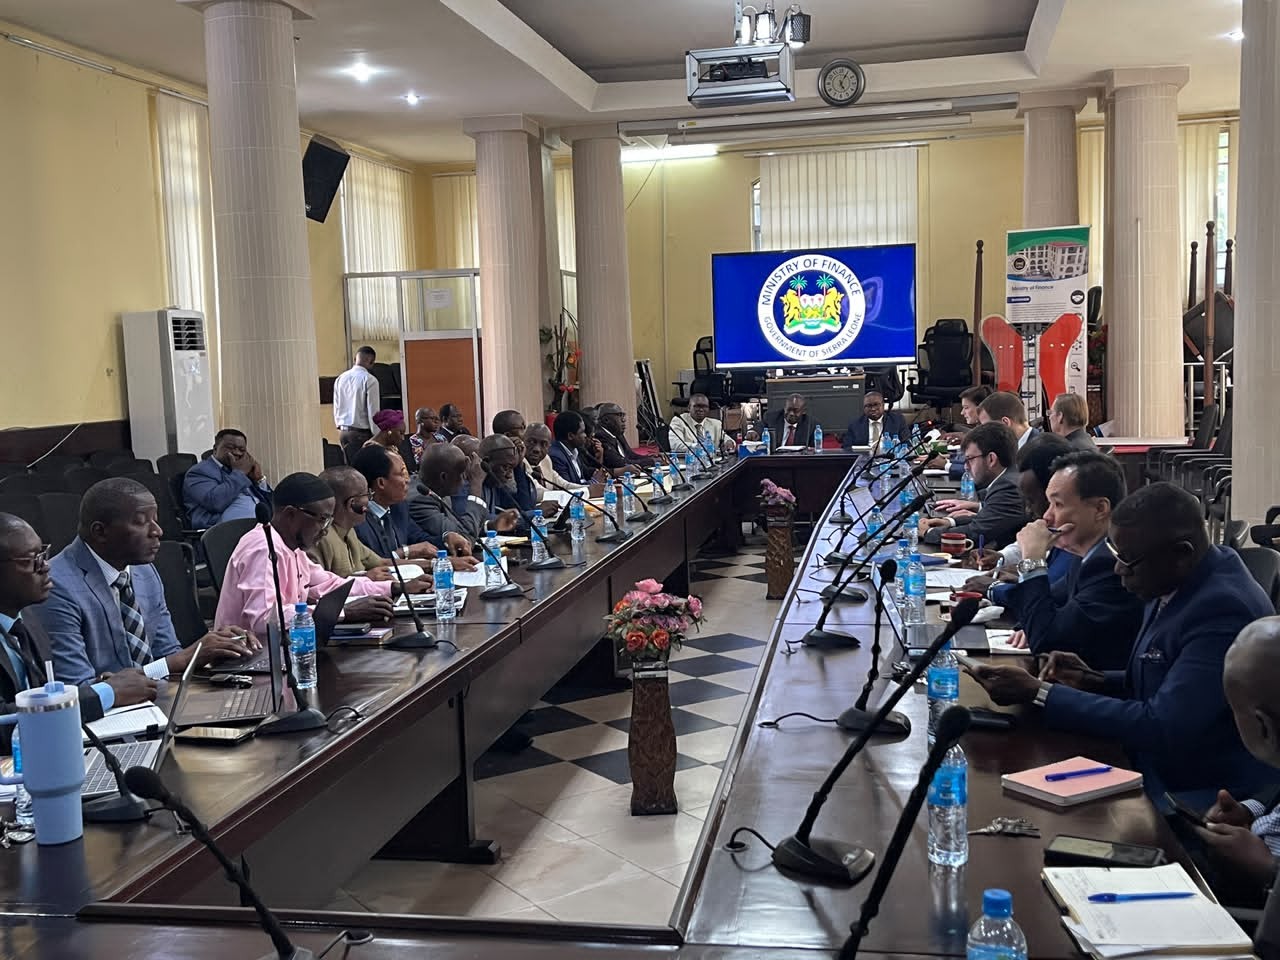
The review mission wrapped up discussions with senior officials from the Ministry of Finance, the Bank of Sierra Leone and the National Revenue Authority during a meeting held at the Ministry of Finance in Freetown on Tuesday, 10th November 2026.
Addressing the meeting, the IMF Mission Chief, Jeta Menkulasi. said the team had engaged with a broad range of economic and governance institutions and observed notable progress in Sierra Leone’s economic reform agenda over the past three years. She highlighted improvements in inflation management, fiscal consolidation and the stabilisation of key macroeconomic indicators as evidence of the Government’s commitment to rebuilding the economy.
Despite these achievements, she warned that external shocks, including ongoing tensions in the Middle East, rising global energy and fuel prices, and renewed inflationary pressures, could reverse some of the progress made. She therefore encouraged the Government to sustain reform efforts and implement stronger policy measures to address economic challenges in 2027.
Key discussions during the review focused on public debt management, domestic arrears, foreign exchange reserves, domestic revenue mobilisation and broader governance reforms aimed at strengthening economic resilience.
The IMF Mission Chief thanked the Government of Sierra Leone for its cooperation throughout the review process and expressed optimism that, subject to the fulfilment of agreed actions, the IMF Executive Board would consider and approve the review and associated disbursement during its December meeting.
Welcoming the mission’s findings, Minister of Finance Kerefa A.F. Kargbo reaffirmed Government’s commitment to implementing reforms that support sustainable economic growth and macroeconomic stability.
He acknowledged that external shocks continue to pose significant challenges to small and vulnerable economies such as Sierra Leone but noted that the Government remains focused on strengthening public financial management and enhancing economic resilience.
The Minister outlined ongoing efforts to improve arrears and contract management, strengthen cash management systems, regulate foreign exchange expenditure and increase foreign exchange repatriation by major companies operating in the trade, agriculture and mining sectors.
Governor of the Bank of Sierra Leone, Dr Brima Stevens, provided updates on monetary policy implementation, developments in the foreign exchange market and the country’s reserve position, which currently stands at approximately 1.8 months of import cover.
Financial Secretary Matthew Dingie said discussions between the Government and the IMF had been constructive and expressed confidence that Sierra Leone’s performance under the programme would receive favourable consideration from the IMF Executive Board, paving the way for the anticipated disbursement.
The Extended Credit Facility, approved on 31 October 2024, supports Sierra Leone’s programme of fiscal consolidation, macroeconomic stability, debt sustainability, monetary policy reforms and structural transformation.
The Resilience and Sustainability Facility, approved on 18 June 2026 with financing of SDR 155.55 million (approximately US$211.5 million), is designed to help Sierra Leone strengthen climate resilience and advance reforms that support long-term economic stability.
The fourth ECF review assessed programme performance as of 30 June 2026 and provided an opportunity for both the Government and the IMF to evaluate progress, address outstanding policy commitments and agree on priorities for the remainder of the programme period.
Copyright –Published in Expo Times News on Wednesday, 11th November 2026 (ExpoTimes News – Expo Media Group (expomediasl.com)